Two numbers landed 24 hours apart this week and Jason Lemkin put them side by side. This is a field note on the line both companies left out, from a migration where it was the first slide.
The short version
Per Jason Lemkin's October 31 post, ServiceNow's shares fell 26.9% after a Q3 with subscription revenue of $3,988 million up 21%, backlog growth guided down to 18.5%, operating margin at 9.4% from 16.8%, and gross margin at 70.5% from 77.3% a year earlier; the next morning Bret Taylor and Clay Bavor posted Sierra's $400M+ ARR, with $150M+ added in the quarter and five months to double from $200M. Lemkin's rule for founders is that investors accept margin compression when growth accelerates and punish it when growth stays flat. The variable is not growth. ServiceNow's call says 50% of net new business is now non-seat pricing, which on the pricing migration I ran is the middle of the road, where blended gross margin went from 80% to a trough of 58 to 62% in quarter four and back to 71% by month 22 when outcome revenue reached 91%. My board saw the curve, with the trough sized in advance, every quarter for 24 months. The line missing from ServiceNow's call, and from Sierra's post, is the trough and the month it climbs back, and a falling margin with no stated bottom reads as permanent.
What the two posts say
Lemkin's post is the better of the two to read, because it does the arithmetic. ServiceNow's quarter was good by most measures: subscription revenue of $3,988 million, up 21%, 19 transactions over $5 million in net new ACV, the year-end AI target raised for the second time to $1.7 billion, free cash flow margin guidance up to 36%. The adjusted EPS miss was two cents. What moved the stock, in his reading, was three things. Backlog growth guided down from 21% to 18.5%, with CFO Gina Mastantuono saying about half of the cRPO beat came from renewals pulled forward from Q4 by a July 1 pricing change. Reported operating margin down to 9.4% from 16.8% a year earlier. And gross margin down to 70.5% from 77.3%, part acquisitions, part the cost of serving AI.
Then Sierra. The post by Bret Taylor and Clay Bavor is short and has no margin in it. $400M+ in ARR two and a half years after launch. $150M+ added in Q3, more than all of last year. Six months to double from $100M to $200M, five months to double from $200M to $400M. Almost half the Fortune 50. A $40B+ retailer from first meeting to live agent in 27 days. And the pricing line: you pay for outcomes, not tokens, a loan refinanced, a claim paid, a sale closed, a customer retained.
Lemkin's five takeaways for founders end with the one I want to argue with: "Watch gross margin as AI ships. ServiceNow's gross margin fell from 77.3% to 70.5% in a year. Investors will accept margin compression when growth accelerates, and punish it when growth stays flat."
The variable is not growth
I ran the migration ServiceNow is in the middle of. The whole bill is in Lovable Isn't Ready for Outcome Pricing. Here Is the 21-Month Bill. and the day it broke is in Field Report: What Broke When We Killed Our Per-Seat Tier. The short form: a $40M ARR SaaS, per-seat to hybrid outcome pricing, 21 months from the decision to the day the per-seat tier sunset.
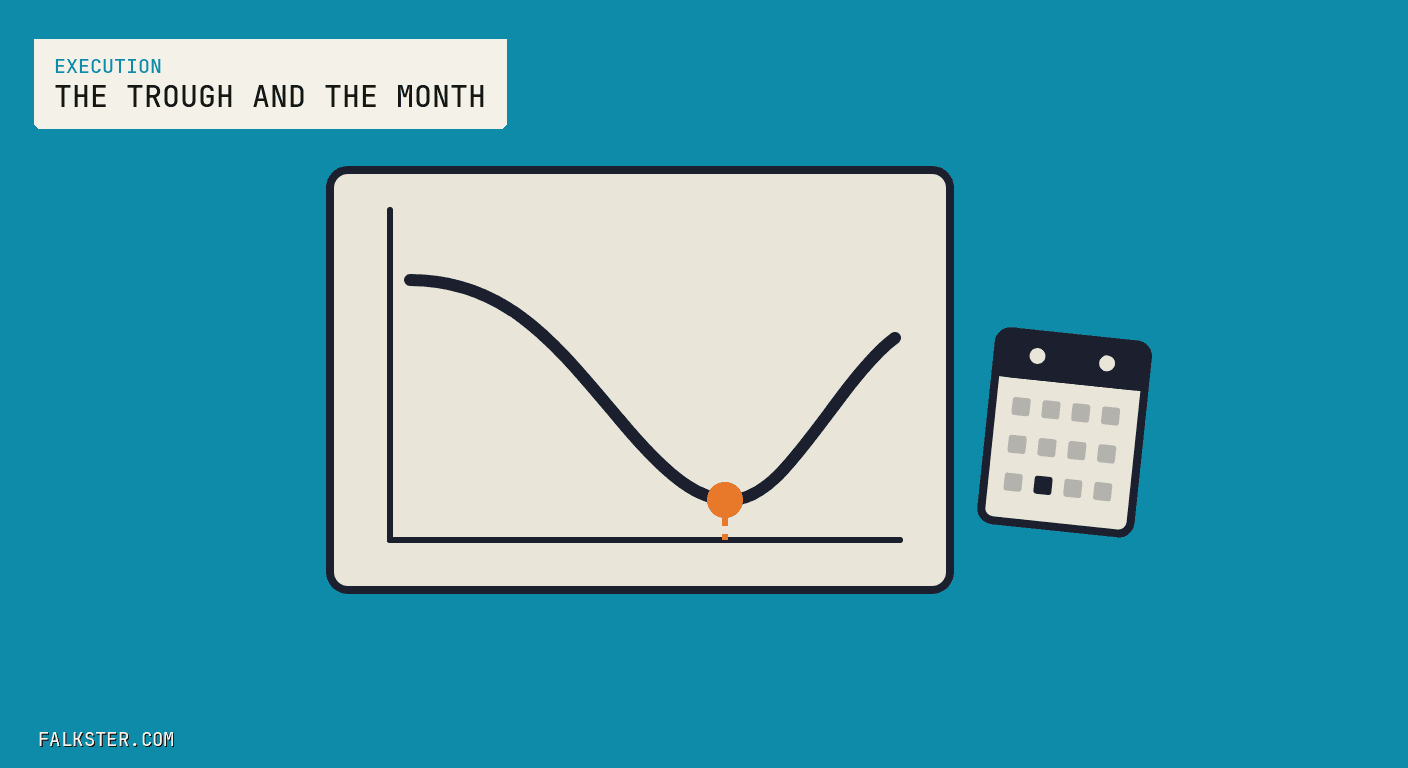
The curve from Pricing Migration: The 18-Month Quarterly Playbook is the part that matters here. Blended gross margin starts at 80%. Quarter three, 65 to 68%. Quarter four, the trough, 58 to 62%, with the sunset date announced twelve months out. Quarter five, recovering toward 65%. Quarter six, back above 70%. The actual migration recovered to 71% by month 22, when outcome revenue reached 91% of the total.
Now put ServiceNow on that curve. The call, as Lemkin reports it, says 50% of net new business is now sourced from non-seat pricing, tokens and connectors included, and Bill McDermott says customers like the predictability of seats with consumption layered on top. Half of net new on the new model is the middle of my road. It is the quarter where the margin is still going down and the bottom is still ahead. A gross margin of 70.5% at that point is roughly where mine sat in quarter three.
So 70.5% is a migration margin. It is not a verdict on whether AI is costing ServiceNow more than it adds. It is a waypoint on a curve that has a known shape, and the market read it as a verdict because nobody on the call said where the bottom is or when the line turns.
That is the disagreement with Lemkin's rule. Growth accelerating does not make investors accept compression. Sierra's growth is accelerating and Sierra publishes no margin at all, which is a different way of not answering the question, and the same gap I named in Anthropic's S-1 Has No Gross Margin Line. Your AI Product Needs One. last week. What makes a falling margin survivable is that the person reading it already knows the trough and the month.
The three slides
My board saw three slides every quarter for 24 months. The change: what moved to outcome pricing this quarter and what did not. The curve: the blended gross margin line with the trough drawn in before it happened, 58 to 62% in quarter four, and the recovery drawn in after it. The leading indicators: the share of net new on the new model, the share of revenue, the dispute count against plan.
The trough was sized in quarter one, in the CFO conversation that the playbook puts first. So when the number arrived in quarter four, it had already been presented three times. Nobody in the room learned the margin from the margin. They had been watching a line go where it was drawn to go.
That is the line missing from both posts this week. ServiceNow gave the market a falling margin with no bottom. Sierra gave it accelerating growth with no margin. Lemkin's rule explains the first stock move and would not have predicted it, because a company at 20% growth with a published trough and a published turn is a different story from the same company without them.
Under SaaS to AI Business Models the claim is that the price has to move to the outcome and the margin structure moves with it. The second half of that sentence is the part nobody wants to present. ServiceNow is presenting it by accident, one quarter at a time. The alternative is to present it on purpose, once, with the bottom and the month on the slide.
This week, if your AI product is compressing gross margin: write down the trough you expect, as a range, and the quarter you expect the line to turn. Put both on the next board slide, next to the share of net new on the new model. A falling line with no stated bottom reads as permanent to everyone outside the building, and this week it cost a $16 billion subscription business a quarter of its value.
Related answer: How far should gross margin fall during an AI pricing migration?
Sources: Jason Lemkin, "SaaS Isn't Dead. Old SaaS Is Dead: Sierra Adds $150M ARR in One Quarter While ServiceNow Drops 27% in a Day," SaaStr, October 31, 2026, read in full; ServiceNow's Q3 figures, the quotes from Bill McDermott and Gina Mastantuono, and the Gartner and IDC forecasts are as he reports them, and the earnings call and the forecasts were not opened. Bret Taylor and Clay Bavor, "Our customers' ambition is accelerating our growth," Sierra blog, October 30, 2026, read in full. Falk Gottlob, "Lovable Isn't Ready for Outcome Pricing. Here Is the 21-Month Bill." (October 16, 2026), "Field Report: What Broke When We Killed Our Per-Seat Tier," "Pricing Migration: The 18-Month Quarterly Playbook," and "Anthropic's S-1 Has No Gross Margin Line. Your AI Product Needs One." (October 29, 2026).
Frequently asked
What happened to ServiceNow and Sierra this week?+
Per Jason Lemkin's October 31, 2026 SaaStr post, ServiceNow's shares fell 26.9% on Thursday after its Q3 report: subscription revenue of $3,988 million up 21%, the AI target raised to $1.7 billion, free cash flow margin guidance at 36%, but backlog growth guided down from 21% to 18.5% with about half the cRPO beat from renewals pulled forward by a July pricing change, reported operating margin at 9.4% from 16.8%, and gross margin at 70.5% from 77.3% a year earlier. On Friday, Bret Taylor and Clay Bavor posted Sierra's Q3: $400M+ in ARR, $150M+ added in the quarter, six months to double from $100M to $200M and five to double from $200M to $400M, almost half the Fortune 50 as customers, and a $40B+ retailer live in 27 days.
What is Jason Lemkin's claim about gross margin?+
His fifth takeaway for founders: watch gross margin as AI ships, because investors will accept margin compression when growth accelerates and punish it when growth stays flat. He reads ServiceNow's quarter as the market deciding AI is costing it margin faster than it adds growth. I think the variable is not growth but whether the company has named the trough and the month it climbs back.
What does your own migration curve look like?+
At a $40M ARR SaaS moving from per-seat to outcome pricing, the playbook's blended gross margin starts at 80%, reaches 65 to 68% in quarter three, bottoms at 58 to 62% in quarter four, recovers toward 65% in quarter five, and is back above 70% in quarter six. The migration I ran took 21 months from the decision to the day the per-seat tier sunset, and by month 22 outcome revenue was 91% of the total and blended gross margin was back at 71%.
Why is 70.5% a migration margin?+
Because ServiceNow's own call, as Lemkin reports it, says 50% of net new business is now sourced from non-seat pricing, including tokens and connectors. On my curve, half of net new on the new model is the middle of the road, where the margin is still falling and the trough is ahead. A gross margin of 70.5% at that point is where my blended margin sat in quarter three. The problem is not the number. It is that nothing on the call said where the bottom is or when the line turns.
What should a board see during an AI pricing migration?+
Three slides every quarter for 24 months: the change, the curve with the trough sized in advance, and the leading indicators. Mine saw the 58 to 62% trough before it happened, so when the number arrived it had already been presented. That is the difference between a waypoint and a verdict, and it is what ServiceNow's call did not give and Sierra's post, with no margin line at all, does not give either.
Comments (0)
Sign in with LinkedIn to leave a comment.
Sign in with LinkedIn